Many California homeowners assume workers’ compensation insurance is only something businesses need.
But what happens if someone you regularly employ at your home gets hurt while working for you?
A housekeeper slips on a wet floor. A domestic worker falls down the stairs. A residence employee suffers an injury while performing work around your home.
Depending on the circumstances, the homeowner could have responsibilities under California workers’ compensation law.
That’s why it’s important to understand whether your homeowners insurance includes Workers’ Compensation – Residence Employees coverage.
What Is Workers’ Compensation Coverage on a Homeowners Policy?
Some California homeowners policies include or can be endorsed with Workers’ Compensation Residence Employees coverage.
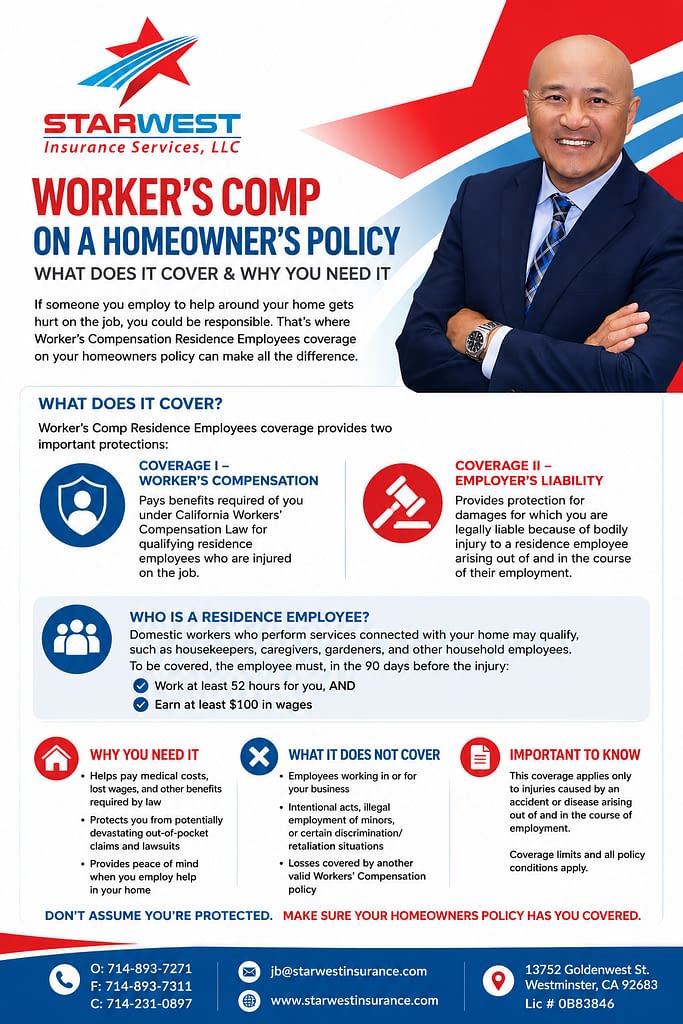
The Mercury California endorsement we reviewed provides two important layers of protection.
Coverage I – Workers’ Compensation
The insurance company agrees to pay benefits required of the insured under California Workers’ Compensation Law for qualifying residence employees.
Coverage II – Employer’s Liability
The policy also provides protection for damages for which the insured is legally liable because of bodily injury suffered by a residence employee. The injury must arise out of and in the course of the employee’s work for the insured.
That distinction is important.
It’s not simply another version of the Personal Liability or Medical Payments to Others coverage found on a homeowners policy. It’s specifically designed to address qualifying employment-related injuries involving residence employees.
Who Is Considered a Residence Employee?
Think about people who perform services connected with maintaining or using your residence.
Depending on the circumstances and policy definitions, this could potentially involve domestic workers performing household or residential services.
For example:
- Housekeepers
- Domestic helpers
- Certain caregivers
- Household employees
- Other workers performing qualifying services around the residence
However, not everyone who comes onto your property to perform work automatically becomes your residence employee.
An independent contractor or an employee of a separate company may be treated differently. The actual employment relationship matters.
There’s an Important Eligibility Requirement
The Mercury endorsement has a very specific requirement.
A residence employee is covered if, during the 90 calendar days immediately before the injury, that employee has:
1. Worked for the insured for at least 52 hours; AND
2. Earned at least $100 in wages.
That’s important because this isn’t simply blanket workers’ compensation protection for every person who performs a task at your house.
Coverage depends on the policy language and the facts surrounding the employment.
Example: Your Housekeeper Gets Hurt
Suppose you employ someone to clean your home regularly.
While cleaning the house, the employee falls down the stairs and suffers a serious injury.
If that person qualifies as a residence employee under the policy and California law, the workers’ compensation endorsement can become extremely important.
Under Coverage I, Mercury agrees to pay benefits required of the insured under California Workers’ Compensation Law.
Coverage II can also address certain damages for which the homeowner becomes legally liable because of bodily injury arising from the residence employee’s work.
Without appropriate coverage, a homeowner could potentially find themselves dealing with an employment-related injury without the protection they assumed their homeowners policy provided.
What About a Gardener or Handyman?
This is where homeowners need to be careful.
Hiring a landscaping company with its own employees and workers’ compensation insurance is very different from personally employing an individual to work at your home.
The same issue can arise with handymen, caregivers, housekeepers and other workers.
Don’t automatically assume:
“They’re working at my house, so my homeowners insurance covers them.”
Likewise, don’t automatically assume:
“They’re an independent contractor, so I have no responsibility.”
Whether someone qualifies as a residence employee and whether workers’ compensation benefits apply depends on the facts, California law and the policy language.
For contractors and service companies, homeowners should also consider requesting proof of appropriate insurance before work begins.
Why Isn’t Regular Homeowners Liability Enough?
This is probably the biggest misconception.
A typical homeowners policy provides Personal Liability Coverage, but an injury involving someone working as your employee can raise an entirely different insurance issue.
Workers’ compensation laws are designed specifically around workplace injuries.
The Mercury residence employee endorsement goes beyond ordinary premises liability by agreeing to pay qualifying benefits required under California Workers’ Compensation Law.
That’s why I don’t like relying solely on a homeowners policy’s general liability coverage when a household has qualifying residence employees.
What Does Employer’s Liability Cover?
The endorsement’s Coverage II addresses damages for which the insured becomes legally liable because of bodily injury to a residence employee.
The bodily injury must arise out of and in the course of employment, and it may result from an accident or disease.
The policy’s total liability is subject to the limit shown on the declarations. For bodily injury by disease, the endorsement states an aggregate maximum of $500,000.
Always check the declarations for the actual limits applying to your particular policy.
What Isn’t Covered?
Workers’ compensation coverage on a homeowners policy isn’t unlimited.
For example, the Mercury endorsement specifically excludes bodily injury arising out of the insured’s business pursuits.
That’s an important distinction.
If someone is actually working for your business, you shouldn’t expect a homeowners residence employee endorsement to substitute for a commercial workers’ compensation policy.
The endorsement also contains other exclusions and conditions, including provisions involving serious and willful misconduct, illegally employed minors, certain employment discrimination/retaliation situations, contractual liability and disease claims.
What If Another Workers’ Compensation Policy Already Covers the Worker?
The Mercury endorsement addresses this as well.
It says the residence employee coverage does not apply to a loss for which valid and collectible Workers’ Compensation or Employers’ Liability insurance applies.
For example, if you hire a properly insured company and its employee gets hurt while performing work, that company’s workers’ compensation policy may be the applicable coverage.
This is another reason homeowners should ask contractors and service companies for certificates of insurance.
Why I Prefer Homeowners Policies That Include Residence Employee Workers’ Compensation
When comparing homeowners insurance, price shouldn’t be the only consideration.
Two policies can have similar dwelling limits and deductibles while providing very different additional protections.
If you regularly employ someone around your residence, I would specifically ask:
Does my homeowners policy provide Workers’ Compensation coverage for qualifying residence employees?
If the answer is no, it’s worth understanding the potential exposure before choosing the cheapest policy.
An accident involving a worker can be much more financially significant than the small difference in premium between two homeowners insurance options.
Don’t Confuse Workers’ Comp With Coverage for Construction Projects
There’s another important distinction.
Residence employee workers’ compensation should not be treated as a replacement for insurance required for a major remodel, construction project, general contractor or business operation.
If you’re undertaking significant construction, you may need to consider things such as:
Builder’s Risk / Course of Construction • Contractor’s General Liability • Commercial Workers’ Compensation • Umbrella/Excess Liability
The correct insurance structure depends on who is doing the work and the nature of the project.
Shopping for Homeowners Insurance in California? Look Beyond the Premium.
A homeowners policy should protect more than the structure itself.
When we compare home insurance for our clients, we look at important coverages such as:
Dwelling Replacement Cost • Personal Liability • Water Backup • Loss Assessment • Personal Property • Loss of Use • Extended Replacement Cost • Workers’ Compensation for Residence Employees
The cheapest home insurance policy isn’t necessarily the best policy if important protections are missing.
At StarWest Insurance Services, we help California homeowners compare coverage—not simply premiums—so they can understand what they’re actually buying before a claim happens.
StarWest Insurance Services
Insurance Made Easy
Westminster & Irvine, California
CA License #0B83846
Call: (714) 893-7271