If you use your personal vehicle to earn money through Uber, Lyft, DoorDash, or another app-based delivery or ride service, don’t automatically assume your personal auto insurance covers you.
One of the biggest insurance mistakes gig drivers make is believing, “I have full coverage, so I’m covered no matter what I’m doing.”
That may not be true.
Your personal auto policy is primarily designed for personal use, not commercial activities. The Mercury Insurance Ride-Hailing FAQ explains that personal auto coverage generally applies when the vehicle is being used personally and the ride-hailing app is off. Once a driver becomes engaged in ride-hailing activity, personal-policy exclusions can create a significant coverage gap.
How Uber & Lyft Insurance Works
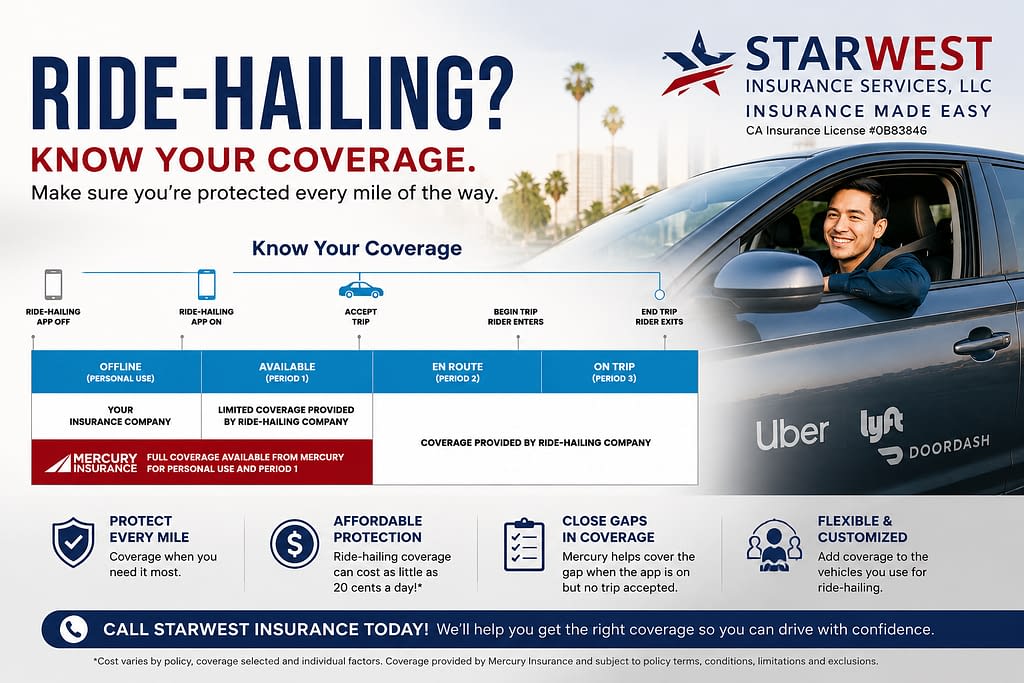
For ride-hailing, it helps to understand the different stages of a trip.
Personal Use — App OFF
You’re driving to work, going shopping, visiting friends, taking the kids somewhere, etc.
Your ride-hailing app is OFF.
This is ordinary personal use, and your personal auto policy generally applies subject to its terms, conditions, limits and exclusions.
Period 1 — App ON, Waiting for a Ride
You turn on Uber or Lyft and are waiting for a customer request, but you haven’t accepted a trip yet.
This is where one of the most important insurance gaps can occur.
Mercury’s FAQ specifically identifies Period 1 as the time after the TNC app has been turned on but before a passenger has been accepted.
According to Mercury, a standard personal auto policy does not cover commercial driving, while the TNC company’s protection during this period may be limited. This can leave the driver responsible for damage to their own vehicle following an accident.
Period 2 — Ride Accepted, Driving to Pick Up the Passenger
Once you accept a passenger and are driving to pick them up, you enter Period 2.
The TNC’s commercial insurance is generally the primary coverage during this stage. Mercury’s diagram on page 1 shows the transition from personal insurance/Period 1 protection to coverage provided by the ride-hailing company once a trip has been accepted.
Period 3 — Passenger in the Vehicle
Once the passenger enters your vehicle, you are in Period 3. This continues while transporting the passenger through the end of the trip.
Again, the ride-hailing company’s commercial insurance is generally responsible during this portion of the trip, subject to its terms and limitations.
What Does a Ride-Hailing Endorsement Do?
This is where specialized TNC or ride-hailing coverage becomes important.
Mercury explains that its ride-hailing coverage is designed to fill the Period 1 gap—when the app is turned on but the driver has not yet accepted a fare. Combined with the TNC’s commercial coverage, this is designed to protect the driver through the different stages of ride-hailing activity.
With Mercury’s ride-hailing coverage, if a covered accident occurs during Period 1, coverage can extend up to the policy limits for liability and, depending on the policy’s terms and coverages selected, damage to the driver’s own vehicle.
Even better, Mercury states that eligible customers can add its ride-hailing insurance for as little as 20 cents per day, although the actual price depends on the policy and coverage selected. You must have a Mercury personal auto policy to add the coverage.
What About DoorDash, Uber Eats and Other Delivery Apps?
This is an important distinction.
The Mercury PDF provided here specifically discusses Transportation Network Companies (TNCs) carrying passengers, such as Uber and Lyft. It does not specifically confirm coverage for DoorDash, Uber Eats, Instacart or other food/package delivery services.
Delivery driving can still be considered a business or commercial use of your vehicle, however, so you should never assume that a ride-hailing endorsement automatically covers delivery activity.
Before driving for DoorDash, Uber Eats, Instacart, Amazon Flex or a similar service, ask your insurance agent to verify whether your specific carrier and policy allow that activity and what endorsement or commercial coverage may be required.
“But Uber or Lyft Gives Me Insurance. Why Do I Need Anything Else?”
Because the coverage provided by the platform and your personal auto policy are not necessarily the same thing.
The potential problem occurs at the transition between personal driving and commercial driving.
For example:
You finish dinner and decide to make some extra money. You get into your car and turn on the Uber or Lyft app.
You haven’t accepted a passenger yet.
Five minutes later, you cause an accident.
Your app was ON, meaning you were no longer simply using the vehicle for personal transportation. But you hadn’t accepted a trip yet either.
That Period 1 gap is exactly what ride-hailing insurance is designed to address.
Multiple Cars? Make Sure the Correct Vehicle Is Covered
Another important point: don’t assume adding ride-hailing coverage to one vehicle automatically covers every car you own.
Mercury states that ride-hailing coverage can be added specifically to the vehicle or vehicles used for TNC activity. If another vehicle is used for ride-hailing, that vehicle needs to be properly added.
Similarly, if another family member listed on the personal auto policy also drives for a TNC, Mercury says that person needs to be added to the ride-hailing endorsement.
The Bottom Line
Does your regular auto insurance cover Uber, Lyft or DoorDash?
For Uber and Lyft, a standard personal auto policy should not be assumed to cover you while you are engaged in ride-hailing. There can be a particularly important gap when the app is ON but you haven’t accepted a passenger yet.
A properly written ride-hailing/TNC endorsement can help address that exposure.
For DoorDash and other delivery services, coverage varies by carrier and policy. The Mercury TNC document reviewed for this article does not establish DoorDash coverage, so it needs to be specifically verified before you start delivering.
Before You Start Driving, Call Us
If you drive—or are thinking about driving—for Uber, Lyft, DoorDash, Uber Eats or another gig-economy service, StarWest Insurance Services can review your auto policy and help determine whether you have the right coverage.
Don’t wait until after an accident to discover that your personal auto policy excluded the activity.
StarWest Insurance Services, LLC
Insurance Made Easy
Serving California drivers since 1995
CA Insurance License #0B83846
Coverage varies by insurance company, policy, endorsement, vehicle use and TNC/delivery platform. This article is for general informational purposes only. Refer to the actual insurance policy and endorsements for coverage terms, conditions, limitations and exclusions.