


📍 Serving Teachers Across Orange County
Helping educators in:
Irvine • Anaheim • Fullerton • Huntington Beach • Santa Ana • Garden Grove • Newport Beach
🧠 Table of Contents
- What Is a 403(b)?
- What Is an IUL?
- IUL vs 403(b): Key Differences
- Why Teachers Face a Retirement Tax Problem
- The “Tax-Free Bucket” Strategy
- Real-Life Examples for OC Teachers
- Pros & Cons Breakdown
- FAQs About IUL & 403(b)
- Who Should Consider an IUL?
- Free Teacher Retirement Review (CTA)
🏦 What Is a 403(b) Plan?
A 403(b) is a retirement plan designed for:
- Teachers
- School employees
- Nonprofit workers
How It Works:
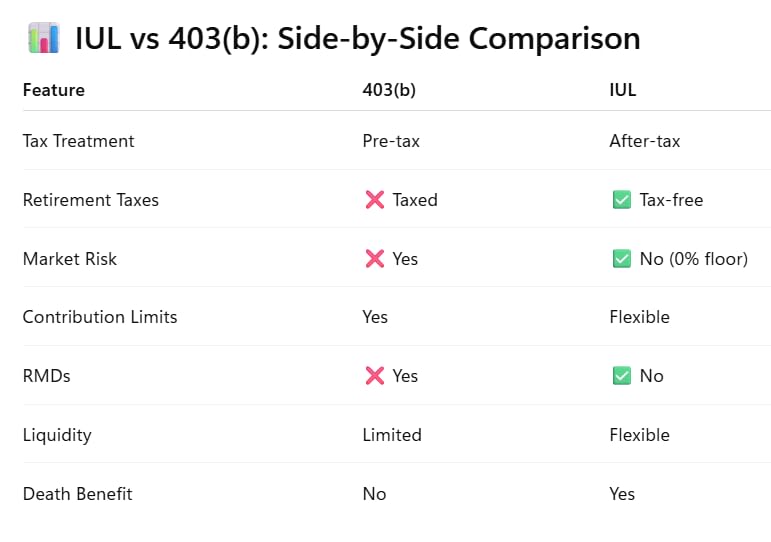
- You contribute pre-tax income
- Funds grow tax-deferred
- Withdrawals are taxed in retirement
Benefits:
✔ Lower taxes today
✔ Possible employer match
✔ Automatic payroll contributions
Drawbacks:
❌ Taxes later (unknown rates)
❌ Market volatility
❌ Required Minimum Distributions (RMDs)
🛡️ What Is an Indexed Universal Life (IUL)?
An IUL is a permanent life insurance policy designed to:
- Grow cash value linked to a market index
- Protect against losses with a 0% floor
- Provide tax-free income in retirement
Key Features:
✔ Tax-free withdrawals (via loans)
✔ Downside protection
✔ No RMDs
✔ Death benefit included
✔ Optional long-term care riders
⚠️ The Hidden Retirement Tax Problem for Teachers
If you’re in Orange County, your retirement may include:
- CalSTRS / CalPERS pension (taxable)
- 403(b) withdrawals (taxable)
- Social Security (partially taxable)
👉 This creates a tax-heavy retirement
The Risk:
- Higher tax brackets later
- Forced withdrawals (RMDs)
- Less control over income
💡 The “Tax-Free Bucket” Strategy
Smart financial planning isn’t about choosing one—it’s about diversification across tax buckets:
3 Types of Money:
- Taxable (brokerage accounts)
- Tax-deferred (403(b), IRA)
- Tax-free (IUL, Roth)
👉 Most teachers are overloaded in tax-deferred accounts
Solution:
Add an IUL to create a tax-free income stream
📉 Real Example (Orange County Teacher)
Scenario:
- $500/month contribution
- 25 years
403(b):
- ~$500,000 value
- After taxes → ~$350,000
IUL:
- ~$400,000 value
- Income → tax-free
👉 The difference = what you keep, not just what you earn
🧾 Pros & Cons Breakdown
403(b)
Pros:
- Employer match
- Easy setup
- Pre-tax savings
Cons:
- Taxable withdrawals
- Market losses possible
- RMDs required
IUL
Pros:
- Tax-free income
- Market protection
- Flexible access
- Death benefit
Cons:
- Requires proper structuring
- Not ideal for short-term investing
❓ Frequently Asked Questions
Is IUL better than a 403(b)?
👉 Not better—different purpose. The best strategy is using both.
Should teachers max out their 403(b)?
👉 Yes—for the employer match first.
Can I lose money in an IUL?
👉 No—due to the 0% floor, you don’t lose money from market downturns.
Is IUL tax-free?
👉 Growth and withdrawals can be tax-free if structured properly.
Is this strategy common in Orange County?
👉 Yes—especially among high-income educators and administrators.
🎯 Who This Strategy Is Best For
✔ Teachers with steady income
✔ Those contributing to a 403(b) already
✔ Individuals concerned about future taxes
✔ People wanting safe growth + tax-free income